

TD Bank (US)
4.2

Managing a bank account from a phone is convenient, but convenience only matters when I still feel in control of what I am doing. I tested TD Bank (US) as a mobile finance app from TD Bank, N.A., and came away with a fairly clear impression: it is most useful for people who already bank with TD and want everyday account access in one place, rather than for someone searching for a general-purpose budgeting tool.
The app is free to use and aimed at everyone, which makes the basic proposition easy to understand. It has been available since 2010, and its current version is 26.10.1.71 for devices running operating system 12 or later. Those details matter less than the practical question: does the app make routine banking feel clear, and does it give me enough control when money is moving in or out?
How much trust does a banking app earn?
My starting point with any finance app is more cautious than with a game or social app. A banking application sits close to sensitive decisions: checking a balance before a payment, reviewing a transaction I do not recognize, or moving money when I am away from a branch. I do not judge it only by how polished the interface looks. I want to know whether the app helps me verify what is happening before I act.
TD Bank (US) benefits from being tied directly to TD Bank, N.A., rather than presenting itself as an independent money-management service that connects to several institutions. That focus can make the experience less flexible than a broad financial dashboard, but it also gives the app a straightforward purpose. If TD is where I keep my accounts, I am not asking it to interpret information imported from somewhere else; I am using the bank’s own mobile channel to handle ordinary banking.
Its popularity also gives the app a useful level of practical reassurance. It has passed five million installs, with an average rating of 4.2 from roughly ninety thousand ratings. I would not treat those figures as proof that every user will have a smooth experience, but they do show that this is an established banking app rather than a niche experiment.
What I appreciate most is that the app’s value is easy to test through small, low-risk tasks. I can open it when I need to inspect recent activity, confirm whether a deposit or payment has appeared, or check available funds before making a purchase. Those moments tell me more than a promotional feature list because they reveal whether the app supports careful decisions or encourages me to tap through too quickly.
Useful for a TD customer, less useful as a standalone finance tool
The strongest audience is someone who already has a TD relationship and wants a mobile extension of that relationship. A student checking an account before buying groceries, a household member reviewing spending before a bill is due, or a customer who travels and does not want to depend on branch hours can all find a sensible reason to install it.
I would not choose it as my first option if my main goal were detailed spending analysis across several banks, investment research, or a unified view of accounts held at different institutions. A dedicated budgeting service may be better for that job, while a bank’s own app is usually better for direct account actions. That distinction is important: TD Bank (US) is primarily about banking access, not replacing every financial tool on a phone.
The app is also a poor fit for anyone who does not use TD Bank. Installing it does not turn it into a neutral wallet or general money tracker. Its usefulness depends on having the appropriate banking relationship and being comfortable managing that relationship through a mobile device.
The everyday workflow I found most practical
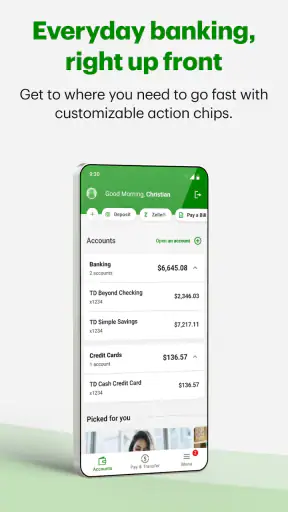
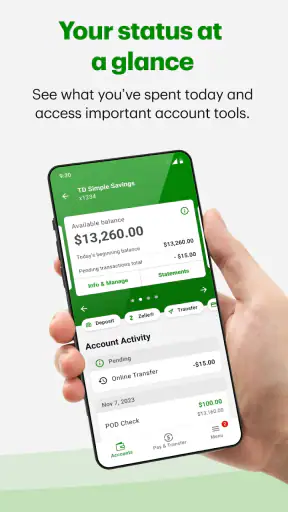
A realistic use case is checking an account before a busy day. I might open the app in the morning, review recent activity, confirm that an expected transaction is visible, and check whether the remaining balance is enough for planned spending. The important habit is to look at the transaction details rather than relying only on the headline balance. A balance can look acceptable while a recently initiated payment or pending activity changes what I can safely spend.
I also found it helpful to use the app as a confirmation step, not as an automatic decision-maker. Before sending money or paying something, I would pause to verify the destination, amount, and account selected. That extra moment is easy to skip on a small screen, yet it is exactly where a banking app should support careful behavior.
Another useful workflow is reviewing activity after a card purchase. Instead of waiting until the end of the month, I can make transaction checking part of my normal routine. If a merchant name looks unfamiliar, I have a better chance of remembering the purchase while the context is fresh. This is not glamorous, but it is one of the more valuable reasons to keep a bank app available.
Controls matter more than a crowded feature list
When I evaluate a finance app, I look for visible account controls and clear choices rather than assuming that a long list of functions equals good security. TD Bank (US) is most convincing when it lets me inspect what is happening and decide what to do next. Account review, transaction checking, and deliberate confirmation are the controls I use most often because they help me catch mistakes before they become larger problems.
I would still avoid treating the phone as a substitute for all other forms of account oversight. For an important transfer, I would check the account context carefully and keep a record of what I intended to do. If something does not look right, I would use the bank’s official support route rather than repeatedly retrying an action or relying on a search result that may not be connected to TD.
This cautious approach is especially relevant when a phone is shared, recently replaced, or used on an unfamiliar network. The app can be convenient, but the surrounding device habits matter too. A strong banking routine includes a screen lock, current operating-system updates, and avoiding account access on devices that other people can freely use.
The minimum operating-system requirement is 12, so anyone with an older device should check compatibility before planning to depend on the app. That requirement is not a criticism by itself; newer software can be necessary for a modern mobile banking experience. Still, it creates a practical limit for people who keep older phones for financial tasks.
Where sensitive moments need extra attention
The most sensitive moments are not limited to signing in. They include reviewing an unfamiliar transaction, choosing between multiple accounts, confirming a payment, and deciding whether a displayed balance is genuinely available for immediate spending. I try to slow down at each of these points, especially when I am distracted or rushing through a checkout line.
Transaction review deserves particular attention. A familiar-looking merchant label can still be confusing if the purchase was made through a different payment processor or by another household member. I would not immediately assume fraud, but I also would not dismiss an unfamiliar entry. The disciplined response is to compare the amount and timing with receipts, subscriptions, and shared spending before escalating it.
Transfers deserve the same care. A mobile interface makes it easy to complete a task while standing in a queue, but that does not mean every task should be rushed. I prefer to prepare the details first, read the confirmation screen fully, and only then submit. This is one of the clearest trade-offs of mobile banking: speed is helpful, but speed without attention increases the cost of a simple selection error.
Privacy is another area where I stay deliberate. I review the app’s visible prompts and device-level access choices instead of granting permissions automatically. I also avoid displaying account information in public and use notifications carefully when other people may see my lock screen. These are user-controlled decisions, and they are worth considering because financial information can be sensitive even when no transaction is being made.
What user agency looks like in practice
For me, user agency means being able to choose when to inspect an account, when to act, and when to stop and verify something through another channel. TD Bank (US) works best when I treat it as an instrument for informed action rather than a place to tap through a checklist.
I recommend turning routine checks into a simple sequence: identify the account, inspect recent activity, confirm the amount, and then decide whether to proceed. That sequence is more reliable than opening the app with a vague intention and immediately selecting the first visible option. It also makes it easier to notice when a transaction belongs to a different account than the one I meant to use.
Another practical tip is to separate monitoring from action. I can look at activity without needing to make a payment or transfer at the same time. Keeping those moments separate reduces the chance that I will act on incomplete information. It is a small behavioral change, but it gives the app a clearer role: first understand the account, then make a decision.
I also prefer keeping a second confirmation method available for unusual situations. If my phone has just been replaced, the connection is unreliable, or an account detail looks different from what I expected, I would not force the task through the app. A branch, official customer-support channel, or another trusted route may be the better choice for a high-consequence issue.
That is where TD Bank (US) differs from many budgeting alternatives. A budgeting app may help me categorize spending or compare several accounts, but it is not necessarily the place where I want to perform a direct banking action. Conversely, a bank app may give me more direct control over that relationship while offering less broad analysis. I would use each type of tool for the job it handles best rather than expecting one app to do everything.
Friction I would want new users to expect
The first source of friction is account dependence. The app is not especially useful until I have the relevant TD banking relationship and can complete the required access process. That is reasonable for a bank app, but it means the experience is not as immediately open-ended as a finance tracker that can be explored without an account.
The second is the responsibility placed on the user. A mobile banking app can show account information and provide ways to manage it, but it cannot decide whether a purchase is sensible, whether a transaction belongs to me, or whether I selected the correct destination. The convenience is real, yet it does not remove the need to read carefully.
The small-screen format can also make detailed review less comfortable than using a larger browser window. When I need to compare several transactions or think through a complicated financial situation, I prefer a larger screen or a more deliberate support conversation. The phone is excellent for quick checks and routine access; it is not automatically the best workspace for every banking problem.
Finally, compatibility can rule out some older devices because the app requires operating system 12 or later. Anyone relying on an aging phone should confirm that it can run the current release before making the app central to their banking routine.
Who should install it, and who should look elsewhere?
I would recommend TD Bank (US) to an existing TD customer who wants a direct, everyday way to inspect accounts and handle routine banking from a phone. It is particularly suitable for people who value quick access but are willing to pause at confirmation screens and review activity regularly.
I would steer a different user toward another option if the main need is a complete financial command center. Someone managing accounts at several banks may prefer a service designed around aggregation. Someone trying to build a detailed spending plan may want stronger budgeting and reporting tools. Someone with an older phone may need a compatible alternative or a non-mobile access method.
I would also advise caution for users who tend to approve prompts without reading them or who share their device casually. The issue is not that mobile banking is inherently unsuitable; it is that account access demands better device and privacy habits than many ordinary apps. If I cannot keep the phone reasonably private and updated, I would reconsider making it my primary banking route.
My cautious verdict on TD Bank (US)
After using TD Bank (US), I see it as a focused banking companion rather than an all-purpose financial planner. Its free availability, established presence, and direct connection to TD Bank, N.A. make it a sensible choice for the bank’s own customers. The average rating of 4.2 across about ninety thousand ratings suggests broad acceptance, while the app’s long availability shows that it has had time to become part of ordinary mobile banking habits.
My recommendation comes with a condition: use it deliberately. Check transactions instead of only balances, verify account choices before submitting anything, and treat unusual activity as a reason to slow down. Those habits make the app more valuable than simply opening it when a payment is due.
The best reason to choose TD Bank (US) is controlled access to your TD banking relationship, not a promise that one app will solve every financial task. For routine checks and everyday account management, I find that focus useful. For multi-bank tracking, deep budgeting, or complex financial decisions, I would pair it with a more specialized tool or choose a different service altogether.
In short, I would recommend it to a TD customer who wants convenience without giving up personal oversight. I would skip it as a general finance app if I did not bank with TD, and I would avoid relying on it blindly even if I did. Used with careful review and sensible device privacy, it is a practical mobile route to everyday banking rather than a replacement for financial judgment.
4.2
33.83K Reviews
Pros
- Mobile check deposit is convenient for everyday banking.
- Customizable alerts help track balances and account activity.
- Bill pay can simplify recurring payments and household expenses.
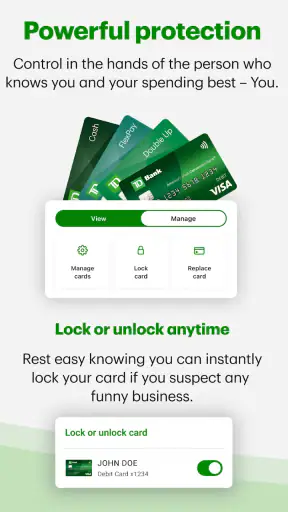
- Card controls let you manage certain debit card settings quickly.
- Branch and ATM locator makes finding nearby services easy.
Cons
- Some features may require an eligible TD account or product.
- App performance can vary after updates or on older devices.
- Mobile deposit limits may restrict larger or frequent deposits.
- Certain support issues may still require contacting the bank directly.
- Availability of branches and ATMs varies significantly by location.


